Do you need earthquake insurance for a Pierce County home?
It isn’t required, but it’s worth a serious look. Washington has one of the highest risks of large, damaging earthquakes in the country, and standard homeowners policies usually don’t cover earthquake damage. Earthquake coverage is added to your policy or bought separately, and deductibles are usually 10%–25% of your building coverage — so it’s built to protect you from a major loss, not small cracks. Whether it makes sense depends on your equity, savings, home’s construction, and how much risk you can absorb.
Every few years a shake reminds us where we live. Pierce County sits near the Cascadia Subduction Zone, the Seattle and Tacoma fault zones, and deep earthquakes like the 2001 Nisqually quake (magnitude 6.8). Yet many homeowners assume their regular policy covers earthquake damage. Usually, it doesn’t.
Here’s how earthquake coverage works in Washington and how to decide whether it belongs in your budget. If you’re new to the area, our Pierce County Relocation Hub covers the basics of living here. For a wider look at local hazards, see how to check a Pierce County property’s hazard risk.
What your homeowners policy does and doesn’t cover
According to the Washington State Office of the Insurance Commissioner, homeowner insurance usually doesn’t cover floods or earthquakes. Earthquake coverage is something you add to your homeowners policy or buy separately.
What earthquake coverage typically pays for
- Repairs to your home
- Damage to personal property
- Debris removal
- Extra living expenses while your home is repaired or rebuilt
- Sometimes: code-upgrade costs, stabilizing the land under your home, and detached structures
What it typically doesn’t cover
- Land itself, vehicles, and damage that existed before the quake
- Landslides, settling, and mudflows unless specifically included
- Floods or tsunamis, even when caused by an earthquake
- Fire — fire damage is handled separately, so ask your agent how your homeowners policy treats fire after an earthquake
The deductible is the big decision
Earthquake deductibles are usually 10%–25% of your building coverage, and there may be separate deductibles for the house, contents, and detached structures. On a home insured for $500,000, a 15% deductible means you pay the first $75,000 of building damage.
That’s why earthquake insurance is best thought of as catastrophe protection. It won’t pay for cracked drywall. It’s there for the scenario where the house is badly damaged and you still owe the mortgage.
Questions that help you decide
- Could you afford to repair or rebuild after a major quake while still paying your mortgage?
- How much equity do you have at risk?
- What is the home built on, and how old is it? Older homes not bolted to their foundations face more risk.
- What would the premium cost each year compared with the protection?
Get quotes at a couple of deductible levels and compare them side by side. Our article on homeowners insurance for move-up buyers covers how to shop your policy.
Lower your risk — and maybe your premium
Some insurers may require or reward basic seismic upgrades:
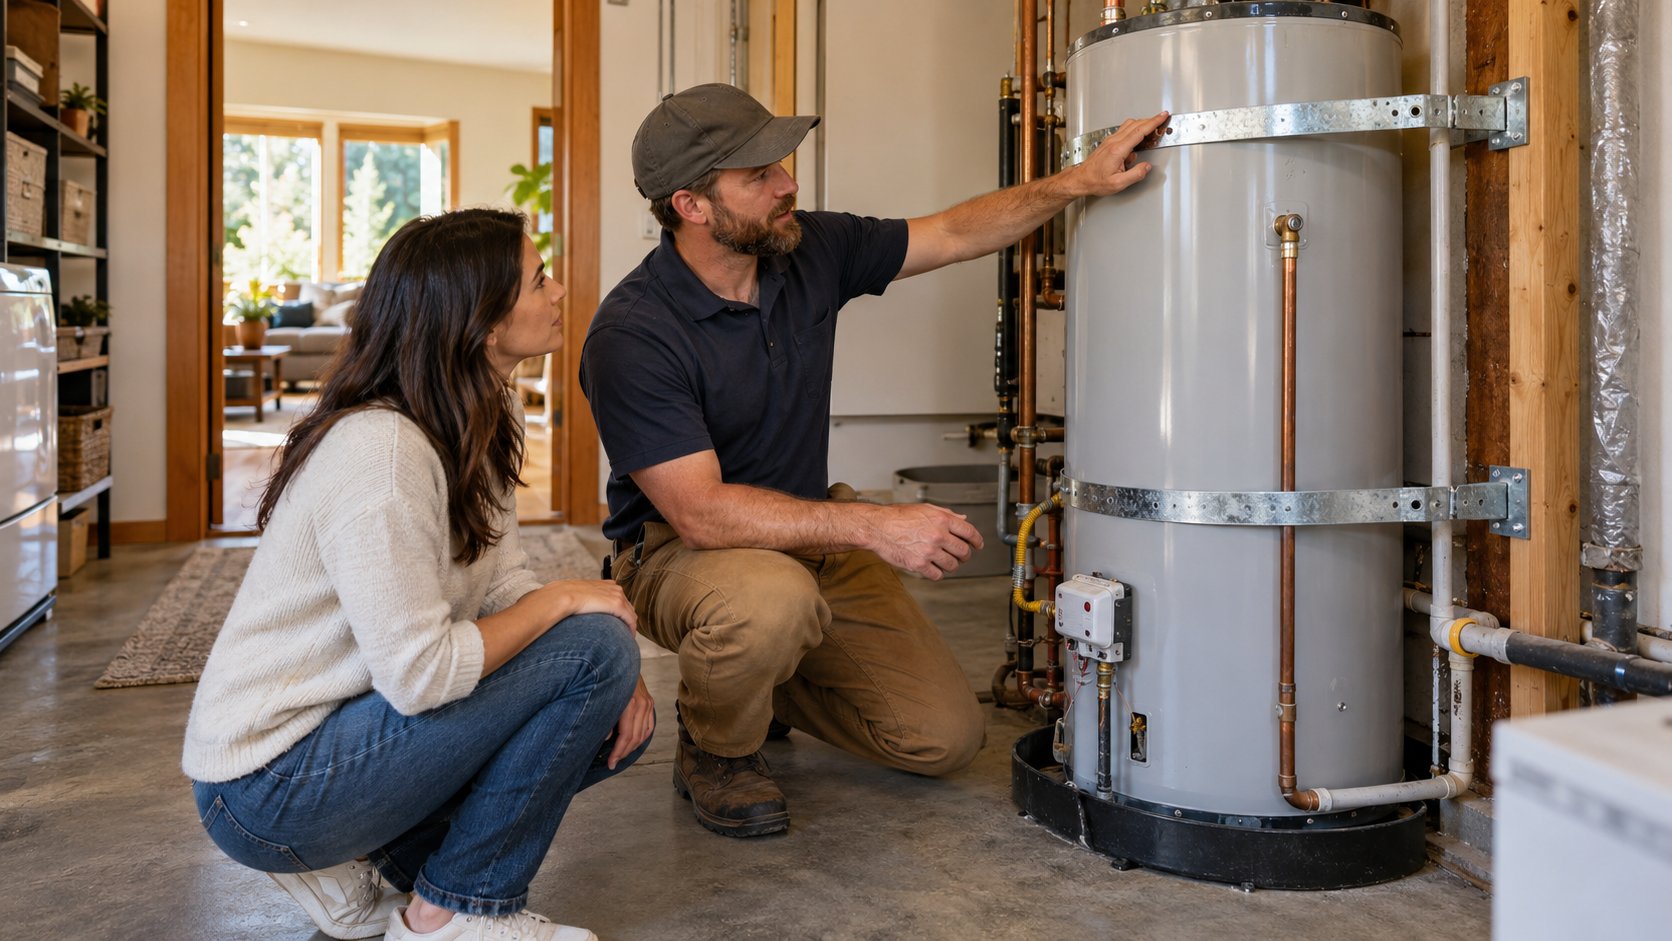
- Strap your water heater with heavy-gauge metal straps anchored into wall studs — the state’s homeowner earthquake guide recommends wrapping the tank 1.5 times and not using plumber’s tape
- Bolt the house to its foundation. Many older homes aren’t bolted, and it’s far cheaper than replacing a foundation after a quake
- Brace cripple walls in crawlspace homes — usually a job for an engineer or experienced contractor
- Secure tall furniture and heavy items
If you’re buying an older home, ask your inspector about seismic details. See our older-home inspection checklist.
Frequently Asked Questions
Does homeowners insurance cover earthquakes in Washington?
Usually not. The Washington Office of the Insurance Commissioner says homeowner insurance usually doesn’t cover earthquakes. You add earthquake coverage to your policy or buy it separately.
How much is the deductible on earthquake insurance?
Earthquake deductibles are usually 10%–25% of your building coverage, and there may be separate deductibles for contents and detached structures.
Is earthquake insurance required to get a mortgage?
Lenders generally don’t require earthquake insurance for single-family homes in Washington. It’s a choice based on your risk tolerance and finances.
Is the Puyallup area at risk for earthquakes?
Yes. Washington has one of the highest risks of large, damaging earthquakes in the country, and Pierce County is affected by the Cascadia Subduction Zone, nearby crustal faults, and deep earthquakes like the 2001 Nisqually quake.
Earthquake insurance is a personal decision, but it should be an informed one — especially when you’re buying or moving up. If you’re house hunting, schedule a call with The Barnard Group and we’ll help you factor insurance and hazard checks into your plan from the start.
About Josh Barnard
Josh Barnard is the founder of The Barnard Group and has spent over 20 years helping families navigate some of life’s biggest moments through real estate. Known for his “Work Hard. Be Kind.” approach, Josh combines expert market knowledge, innovative marketing, and genuine care to help homeowners make confident decisions about their next chapter. Whether someone is buying their first home, moving up, downsizing, or relocating to Pierce County, his mission is simple: serve people well, create unforgettable experiences, and help families build a life they love.
Sources: Washington State Office of the Insurance Commissioner, earthquake insurance guidance; Washington DNR Geological Survey, earthquakes and faults and homeowner’s guide to earthquakes. Not insurance or legal advice — talk with a licensed insurance agent. Researched November 2, 2026.